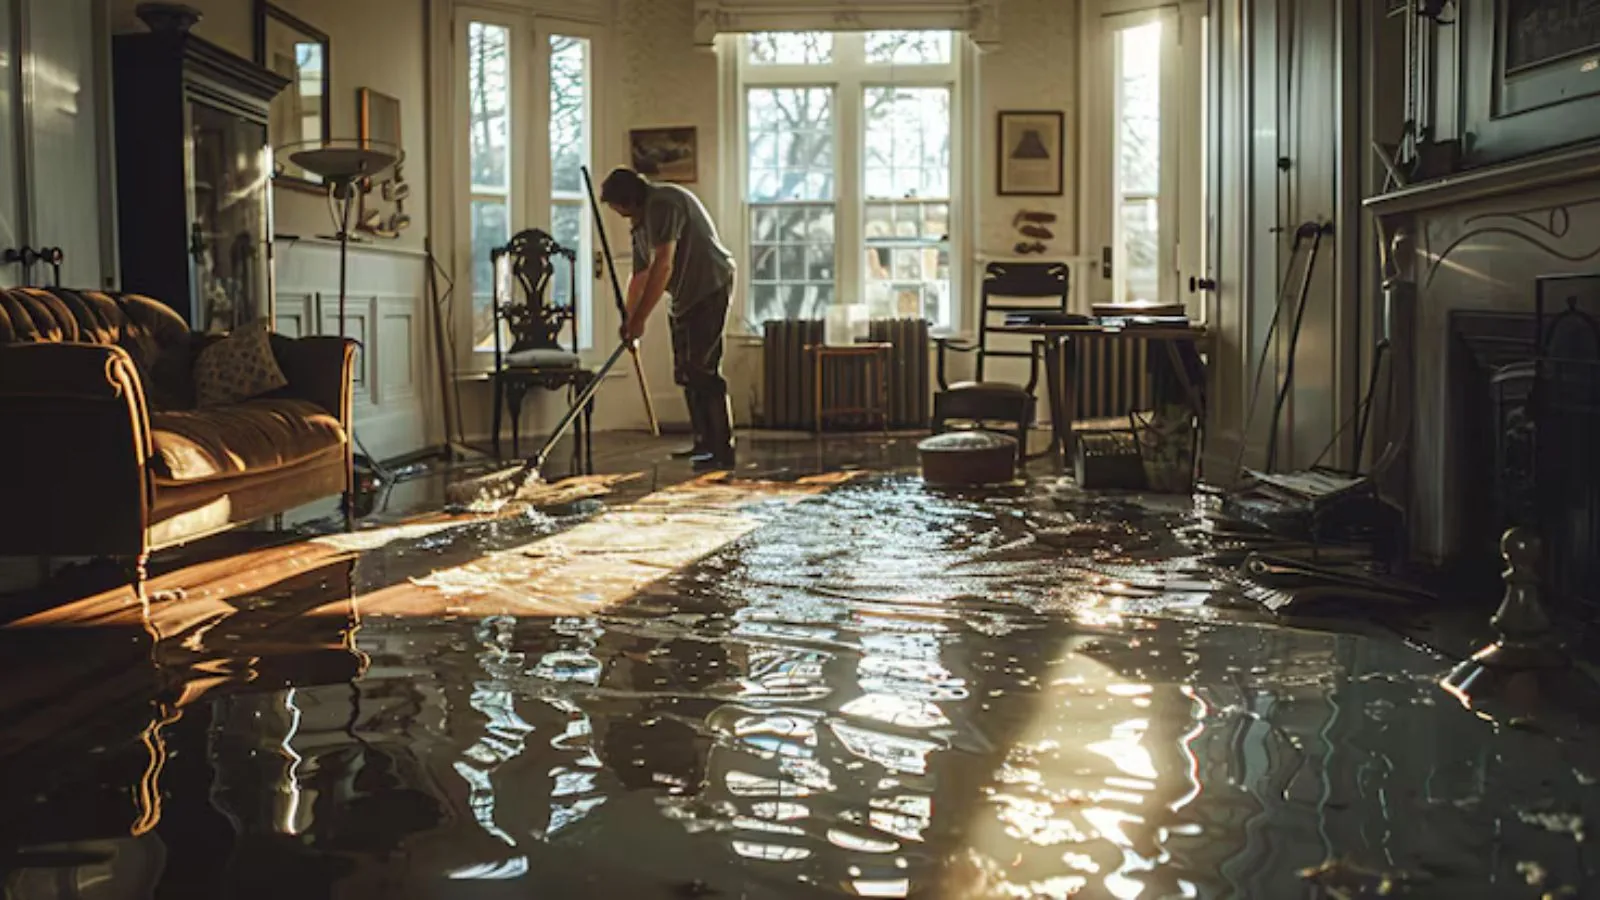
Start with safety and stop the water
Before paperwork, protect people and stop the loss. Shut off the main valve if a line is running, keep power off in wet areas unless you can reach the panel safely and move to a dry part of the house.
Most policies expect you to take reasonable steps to prevent further damage, so a quick mitigation call is part of the claim, not a separate matter.
The first 24 hours, in order
Document
Photograph and video every wet room, the source and any damaged belongings before you move them.
Report
Call your insurer or agent with your policy number, and say you have water damage.
Mitigate
Arrange extraction and drying so the damage does not grow.
Keep records
Start a folder for photos, receipts, names, dates and claim numbers.
What to photograph and write down
| Item | Why it helps |
|---|---|
| Wide shots of each room | Shows the extent of the damage. |
| Close shots of stains and water lines | Shows how high water reached. |
| The failed part or source | Shows the cause of the loss. |
| Serial numbers and labels | Supports contents claims. |
| A dated log of calls and visits | Keeps the timeline straight. |
Working with your adjuster
The adjuster reviews the damage and the scope of repair and decides what the policy covers. Be present when possible, show everything and ask for the estimate in writing.
If you disagree with a decision, ask for the reasoning in writing and check your policy for dispute options. Keep a record of every conversation.
A simple claim log you can copy
Keep one running log from the first phone call. A shared note on your phone works fine, as long as every entry has a date, a name and a result. If the water is still on the floor, structural drying records are worth asking for as well.
| Date and time | Who | What was said or done | Next step |
|---|---|---|---|
| Day 1, evening | Insurer claims line | Reported water damage, got claim number | Adjuster to call within the day. |
| Day 1, night | Restoration crew | Extraction started, photos taken | Drying readings tomorrow. |
| Day 2, morning | Adjuster | Scheduled site visit | Have photos and scope ready. |
| Day 3 | Contractor | Repair scope discussed | Wait for dry readings. |
Mistakes that slow a claim
- Throwing away damaged items before photographing them or before the insurer says you can.
- Waiting several days to call because the damage looked small at first.
- Signing any document you have not read, including work authorizations.
- Naming a cause with certainty when you are not sure, such as calling it a flood.
- Losing receipts for emergency costs, such as equipment, hotel nights or temporary repairs.
If more damage shows up later
Hidden damage sometimes appears days or weeks after the first visit, such as soft flooring or stains on a ceiling. Tell your insurer promptly and send updated photos, because an open claim is easier to add to than a closed one.
Ask your adjuster how they want supplemental items reported, and keep your drying records, since they show what was wet and when.
When you rent or live in a condo
If you rent, your landlord insures the building and you insure your belongings, so you may be filing a renters claim for contents while the landlord handles the structure. Tell the landlord in writing and keep copies.
Condo owners face a split between the association policy and their own, and the master policy usually covers the building shell while your policy covers what is inside your unit. Ask your association for the bylaws section that explains where the line is.
The standard your claim paperwork may cite
Claim paperwork often uses terms from the ANSI/IICRC S500 standard, the published reference for professional water damage restoration. Water category and loss class are the two you will see most.
Ask the company to put those terms in writing next to the photos and readings. Citing the standard is not a claim of certification.
Romulus note: Michigan guidance on claims
Romulus note: what the state says
The Michigan Department of Insurance and Financial Services advises policyholders to report a claim to their insurer or agent, have the policy number ready, protect the property from further loss and take pictures or video of the damage. It also advises not getting rid of damaged items until the insurance company tells you to.
That matters in Romulus because large storms hit many homes at once. The National Weather Service logged 3.31 inches of rain here in about an hour and a half on July 28, 2025, and adjusters can be busy after events like that, so organized records speed things up.
How restoration paperwork helps a claim
A restoration company can give you a written scope, moisture logs and photos that match the work performed. That is useful evidence, but the insurer still makes the coverage decision, and no company can tell you what will be paid.
After a leak, water extraction and drying usually start first, with repair planned after the readings show the structure is dry. Our New Boston and Garden City pages explain how we work in nearby towns.
Common questions
As soon as it is safe. Delays can make the loss worse and can complicate the claim.
Yes. Photograph and video the damage before items are moved or removed, and keep damaged items until told otherwise.
Usually yes. Most policies expect you to protect the property, so document first and then start mitigation.
Keep your records organized, mitigate to prevent more damage and follow up in writing. Many policyholders keep a log of each call.
We provide documentation, but you remain the policyholder and your insurer decides coverage.